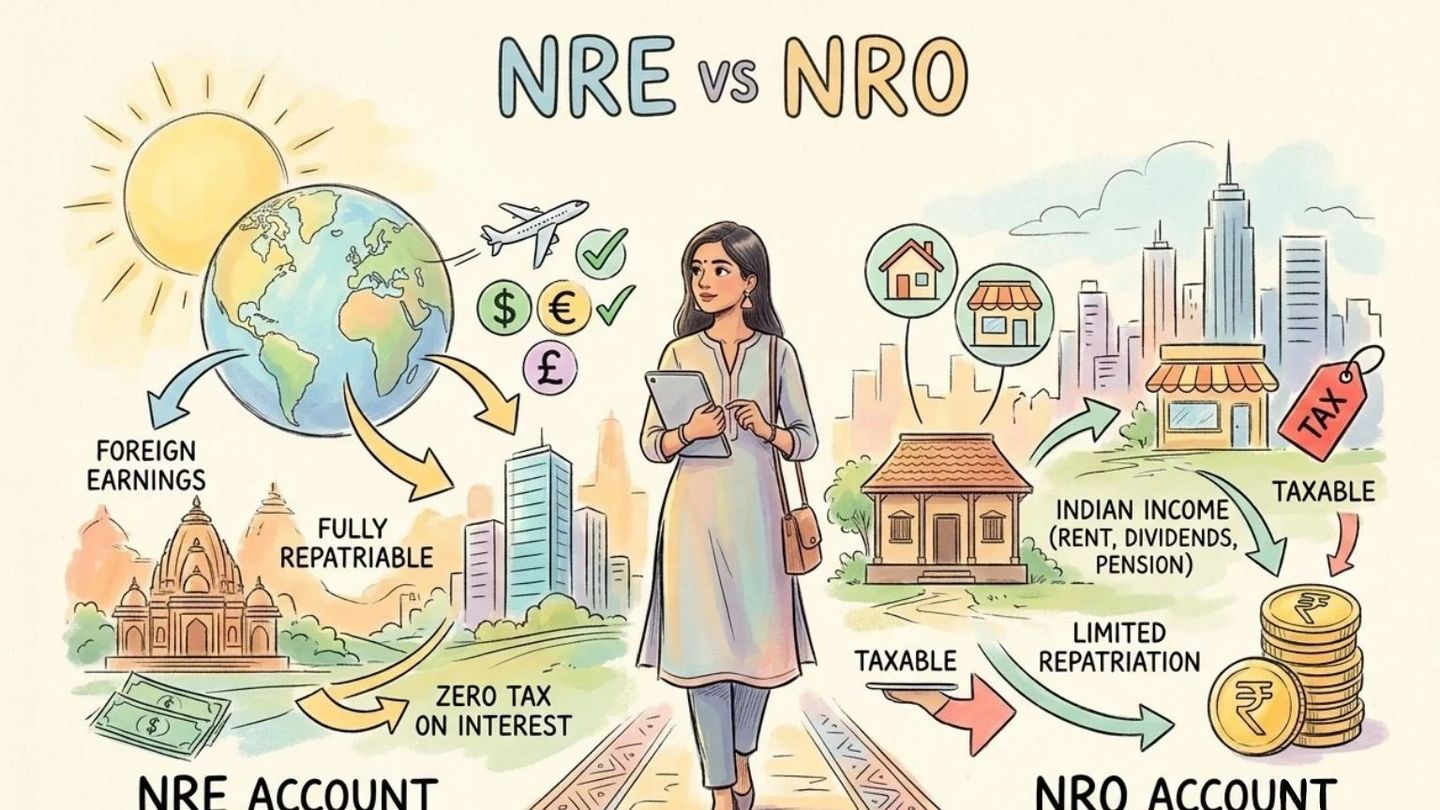
NRE vs NRO Account for NRI Property Transactions: A Complete Guide
If you’re an NRI looking to invest in Indian real estate, choosing the right bank account matters. The account you use to buy property, receive rent, or receive sale proceeds can affect your paperwork, taxes, and how easily you can transfer money overseas. Most NRIs go with either a Non-Resident External (NRE) account or a Non-Resident Ordinary (NRO) account. Both accounts deal in Indian rupees, but each one has its own specific role and benefits.
An NRE account is mainly for holding money earned overseas and sent to India, and you can usually transfer this money back abroad. An NRO account is for managing income earned in India, like rent, dividends, or money from selling property, as long as you follow the rules.
Whether you are buying an apartment in Gurgaon, receiving rent from a tenant in Bengaluru, or selling inherited property in Mumbai, understanding the difference between these accounts can make your financial planning much easier.
Remember, having the right account alone doesn't guarantee you can send money overseas. You also need to consider where the money comes from, the type of transaction, taxes, and FEMA rules.
What is an NRE Account?
A Non-Resident External account lets eligible NRIs keep money in Indian rupees that comes from allowed overseas sources or other qualifying credits. For example, an NRI working in the UK can transfer their eligible overseas income into an NRE account in India. The money is converted into Indian rupees and can usually be used for permitted transactions in India. An NRE account is commonly used for:
- Bringing eligible overseas earnings into India.
- Funding permitted investments and property purchases.
- Maintaining savings in Indian rupees.
- Receiving eligible current income, including rent, where the applicable conditions are satisfied.
- Transferring eligible balances overseas through permitted banking channels.
Key characteristics of an NRE account
Repatriability: You can usually send both the principal and interest from an NRE account back overseas without the annual limits that apply to NRO accounts, as long as you follow the rules and the funds qualify.
Tax treatment: Interest earned on an eligible NRE account is usually not taxed in India, as long as you meet the required conditions. Your residential status and tax laws still need to be checked.
Currency: The account is maintained in Indian rupees. Money remitted in a foreign currency is converted into rupees.
Typical use: Funding eligible property purchases, maintaining overseas savings in India and holding other qualifying funds. An NRE account is helpful if you want to bring money into India but still keep the option to send it back abroad later.
What Is an NRO Account?
An Ordinary Non-Resident account is meant for managing income and money you earn in India.
For example, if you are an NRI who owns an apartment in Gurgaon and get monthly rent from an Indian tenant, you can use an NRO account to receive that money. You can also use an NRO account to receive money from selling eligible property, as long as you follow the banking and foreign exchange rules. Common uses include:
- Receiving rental income from property in India.
- Collecting dividends, pension and other eligible Indian income.
- Receiving property-sale proceeds.
- Paying maintenance charges, property taxes and other Indian expenses.
- Managing eligible domestic receipts and payments.
- Remitting eligible balances overseas under the applicable rules.
Key characteristics of an NRO account
Repatriability: Eligible current income can generally be remitted abroad after applicable taxes have been paid or provided for. Other NRO balances may be remitted under the applicable remittance-of-assets facility, commonly subject to the USD 1 million per financial year limit and the relevant conditions.
Tax treatment: Interest on an NRO account is generally taxable in India, with tax deduction at source potentially applying.
Currency: The account is maintained in Indian rupees.
Typical use: Receiving Indian income, including rent, and managing domestic financial obligations. An NRO account is useful for NRIs with income-generating property in India, or for those who need to receive money from deals or transactions within India.
NRE vs NRO Account: Key Differences
Feature | NRE account | NRO account |
Primary purpose | Maintaining eligible overseas funds in India | Managing Indian income and receipts |
Typical credits | Overseas remittances and other permitted credits | Rent, property-sale proceeds and other eligible Indian receipts |
Repatriation | Eligible balances generally freely repatriable | Subject to the applicable rules, conditions and limits |
Interest taxation in India | Generally exempt if statutory conditions are met | Generally taxable in India |
Property purchase | Can fund eligible purchases using permitted funds | Can fund permitted transactions using eligible rupee balances |
Rental income | Eligible rent can be credited subject to conditions | Commonly used to receive rent |
Property-sale proceeds | May receive funds where the applicable rules permit | Commonly used for sale proceeds that require an NRO route |
Overseas transfer | Generally straightforward for eligible balances | Requires compliance with the relevant remittance procedure |
Which Account Should an NRI Use to Buy Property in India?
Generally, an eligible non-resident Indian (NRI) can arrange the purchase of a permitted property using inward remittances and eligible balances in an NRE or FCNR(B) account, provided the relevant FEMA regulations are followed. You can also use an NRO account to make permitted payments from eligible rupee funds, provided you follow the relevant rules. Choose based on where the money comes from, what the transaction is for, and your investment plans.
Example: Purchasing an apartment in Gurgaon. Consider an Indian resident abroad who is employed in Dubai and intends to buy an apartment costing ₹2.5 crore. The buyer can send the eligible foreign funds to India via banking channels and use the allowed NRE funds to pay the developer or the seller. The buyer should keep the remittance advice, bank statements, allotment documents, the sale agreement, and payment receipts. The bank should make sure that the proposed payment is allowed and in accordance with the relevant rules if the buyer is using money which is already held in an NRO account.
As a practical suggestion, before making a large transfer, check the payment route with your bank and ensure the source of funds can be documented; this is particularly important if the property might one day be sold and the owner plans to send the proceeds overseas. Avoid cash payments and informal transfer arrangements. Property consideration should be paid through permitted banking channels.
Which Account Should an NRI Use to Receive Rental Income?
An NRI who rents out a property in India should consider both banking arrangements and the Indian tax consequences. An NRO account is usually used to collect rent from an Indian tenant, enabling the owner to receive domestic income and pay associated expenses, such as maintenance, property taxes, and other allowable costs.
RBI regulations also allow eligible current income, such as rent, to be deposited into an NRE account, provided the authorised dealer bank is satisfied that the credit is permissible and that the relevant income tax has been deducted or provided for. The distinction matters: an NRI should not assume rent must always remain in an NRO account, nor that any domestic receipt can automatically be moved to an NRE account.
Example: Suppose an NRI owns an apartment that generates ₹1.2 lakh in monthly rent. The owner may collect the rent in an NRO account. The owner can use the account to meet permitted Indian expenses and, subject to the applicable rules, remit eligible current income overseas after accounting for tax. If the owner wants to credit the eligible rental income to an NRE account instead, confirm the bank’s requirements for the source of income and tax compliance.
Rental income remains subject to applicable Indian income tax rules irrespective of the account into which it is credited.
Which Account Should an NRI Use to Receive Property-Sale Proceeds?
This is where the distinction between NRE and NRO accounts becomes especially important.
NRIs should have proceeds from the sale of property in India paid into their accounts through banks authorised for this purpose. The account in which the proceeds are credited and the amount that may be transferred overseas will depend on the property's acquisition history, the origin of the funds used to buy the property and the relevant FEMA regulations.
Property purchased using eligible foreign exchange or NRE funds
Within the RBI framework, proceeds from the sale of immovable property obtained through permitted foreign exchange received through banking channels or from eligible NRE/FCNR(B) funds may be repatriated, provided the relevant conditions are met. For residential property, the relevant direct repatriation facility is restricted to not more than two such properties. The qualifying amount is linked to the permitted funds used for acquisition. The entire resale price should not automatically be assumed to qualify under this route.
Property purchased using rupee funds- In the case where the property was bought with funds in rupees or obtained when the owner was resident in India, the relevant route could be different.
Eligible proceeds may be credited to an NRO account and remitted under the relevant remittance-of-assets facility, subject to the applicable conditions and limits.
Inherited property- Where the property was inherited, the seller should retain the inheritance documents and establish the acquisition history. The applicable remittance provisions and documentation requirements may differ from those for a property purchased using qualifying foreign exchange.
Remember: Having an NRO account doesn’t prove your funds are legally allowed to be sent abroad. Also, putting money into an NRE account doesn’t automatically mean you can freely send those funds out of the country. You still need to meet all the legal requirements for remittance. Before you sell, ask the authorised dealer bank to verify the correct route and required documentation.
Can Money Be Transferred from an NRO Account to an NRE Account?
Transfers from NRO to NRE accounts may be permitted under applicable rules, subject to eligibility, documentation, tax compliance, and relevant remittance limits. For eligible NRI/OCI remittances, the USD 1 million per financial year facility may be relevant, depending on the nature and origin of the funds. The limit applies to the applicable remittance facility and should not be treated as a universal limit on every type of property-sale repatriation. The bank may ask for supporting documents such as:
- Evidence of the source of funds.
- Bank statements and transaction records.
- Property purchase and sale documents.
- Evidence of inheritance, where relevant.
- Income tax returns or evidence of tax compliance.
- Prescribed declarations, certificates and remittance forms.
The exact requirements depend on the transaction and the bank’s compliance review.
An NRI should therefore establish the permitted route before transferring a substantial amount between accounts, particularly where the money represents property-sale proceeds.
How Is Taxation Different for NRE and NRO Accounts?
The tax treatment of the interest earned on the accounts differs, but the account type does not determine the tax treatment of every underlying transaction.
NRE account interest- Interest on an eligible NRE account is generally exempt from Indian income tax while the account holder satisfies the statutory conditions for the exemption.
NRO account interest- Interest on an NRO account is generally taxable in India. The bank may deduct TDS, subject to the applicable law and any relief or lower deduction provisions.
An eligible taxpayer may be able to claim relief under an applicable double taxation agreement, subject to the relevant conditions and documentation.
Property income and capital gains- Rental income and capital gains arising from property transactions are separate from the tax treatment of account interest. For example, rent remains subject to the applicable tax provisions whether it is credited to an NRO account or, where permitted, an NRE account. Likewise, selling a property may trigger capital gains tax even if you deposit the proceeds in an account with repatriation privileges. An NRI should assess property taxation and bank-account taxation separately.
What Documents Should NRIs Maintain?
Good record-keeping can make property transactions and future remittances easier to manage.
For a purchase, retain the purchase agreement, registered deed, bank statements, inward remittance records, allotment documents and payment receipts.
For rental income- Maintain the lease agreement, rent receipts, bank statements, maintenance records and applicable tax documentation.
For a sale- Retain the original acquisition documents, sale deed, evidence of receipt of consideration, bank statements, records of the source of funds and tax documents.
If the property was inherited- Preserve the relevant inheritance and succession records.
These documents can help the bank establish the transaction’s legitimacy, determine the appropriate remittance route and meet applicable compliance requirements.
Common Mistakes NRIs Should Avoid
- Assuming NRE and NRO accounts are interchangeable: They have different permitted credits, repatriation conditions and tax treatment.
- Assuming every NRO balance is freely transferable abroad: Remittance depends on the type of funds, applicable limits and compliance with the relevant regulations.
- Assuming the account determines the tax treatment: Rental income, capital gains and account interest have different tax rules.
- Failing to retain purchase-funding records: Evidence of the original payment route may be important when selling the property and seeking repatriation.
- Transferring funds without checking bank requirements: A transaction may require supporting documents or tax declarations before the bank can process it.
- Waiting until the sale to consider repatriation: Understanding the applicable route at the time of purchase can help avoid problems later.
Conclusion
NRE and NRO accounts serve different purposes in an NRI’s Indian financial arrangements. The NRE account is generally suited to eligible overseas funds and balances that retain their repatriable character. In contrast, the NRO account is commonly used to manage income and receipts arising in India.
For real estate investors, the distinction becomes particularly important when funding a purchase, collecting rent and eventually selling a property. The source of funds, applicable taxes and FEMA rules can influence how the proceeds are handled and whether they can be transferred overseas.
The most effective approach is to plan the banking arrangements as part of the property investment itself. Maintain clear records, use permitted banking channels and consult the authorised dealer bank before making substantial transfers.
At prOPIUM, evaluating a property means looking beyond its purchase price to the complete investment lifecycle, including cash flows, tax implications, ownership costs and exit planning. For NRIs, understanding NRE and NRO accounts is an important part of that process.
FAQ's
What is the major difference between an NRE and an NRO account?
An NRE account is generally used to maintain eligible overseas funds in India, with balances ordinarily repatriable. An NRO account is generally used to manage Indian income and receipts, including rent and property-sale proceeds, subject to the applicable rules.
Can an NRI buy property using an NRE account?
Eligible NRIs can generally use permitted NRE funds to purchase eligible residential or commercial property in India, subject to FEMA regulations and the applicable transaction requirements.
Can an NRI use an NRO account to buy property?
An NRO account may be used for permitted property-related payments from eligible rupee funds, subject to the applicable rules. The bank should confirm that the proposed payment route is permissible.
Should an NRI receive rent in an NRE or NRO account?
An NRO account is commonly used for Indian rental income. However, eligible current income such as rent may also be credited to an NRE account where the authorised dealer bank is satisfied that the credit is permissible and tax has been deducted or provided for.
Can an NRI repatriate property-sale proceeds from an NRO account?
Eligible proceeds may be remitted under the applicable remittance-of-assets facility, subject to the prescribed conditions and limits. The route depends on the property’s acquisition history and the source of the funds.
Is interest on an NRE account tax-free in India?
Interest on an eligible NRE account is generally exempt from Indian income tax while the account holder meets the statutory conditions for the exemption.
Is interest on an NRO account taxable?
Yes. Interest on an NRO account is generally taxable in India, and TDS may apply. Any applicable treaty relief or lower deduction should be assessed separately.
Can money be transferred from an NRO account to an NRE account?
Eligible transfers may be permitted under the applicable regulations, subject to documentation, tax compliance and the relevant remittance limits.
Is the USD 1 million limit applicable to every NRI property sale?
No. The USD 1 million per financial year facility is relevant to specified remittances under the applicable rules. Different conditions may govern qualifying property-sale repatriation under the separate property provisions.
Which account is best for an NRI investing in Indian real estate?
There is no single answer for every investor. The choice depends on the source of funds, whether the property will generate rent, the intended holding period and the plans for sale and repatriation. Many NRIs use both accounts for different purposes.
Disclaimer: This article is for general educational purposes and does not constitute tax, legal or financial advice. FEMA regulations, account eligibility, tax treatment and repatriation requirements may change. NRIs should confirm the applicable requirements with their bank and a qualified professional before undertaking a property transaction.